
The modern freelance economy is characterized by a structural disconnect between the completion of professional services and the receipt of compensation, a phenomenon widely recognized as the income timing gap. For independent contractors, the period between invoicing a client and the actual arrival of funds can span weeks or even months, creating a liquidity crisis even for those with robust annual earnings. This mismatch often forces freelancers to seek external financing to cover essential personal expenses that remain fixed despite the variability of their revenue streams. While borrowing is a common response to these cash-flow interruptions, financial analysts emphasize that the structure of the debt—specifically the distinction between installment loans and short-term payday products—is a critical factor in maintaining long-term fiscal stability.
The Structural Evolution of Freelance Financial Challenges
The rise of the gig economy, which now encompasses approximately 38% of the U.S. workforce according to industry data from 2023, has necessitated a shift in how financial institutions assess risk. Traditional banking models, which rely heavily on W-2 income verification and consistent bi-weekly pay cycles, often exclude freelancers. This exclusion has paved the way for specialized fintech lenders that utilize alternative underwriting methods.
For the independent worker, the challenge is rarely a lack of total income but rather the "lumpiness" of its arrival. A freelancer may secure a high-value contract in January, but if the project concludes in March and the net-30 payment terms extend into April, the individual faces a three-month period of overhead without incoming cash. This creates a reliance on credit that can become predatory if the borrower defaults to high-interest, lump-sum repayment products.

Installment Loans Versus Payday Lending: A Comparative Analysis
Financial experts categorize personal installment loans as a more sustainable alternative to the traditional payday loan model. The primary distinction lies in the repayment architecture. A payday loan typically requires the borrower to repay the entire principal plus interest in a single lump sum, often timed with their next expected deposit. For a freelancer with an uncertain "payday," this requirement can trigger a debt cycle, where the borrower must take out a second loan to cover the first.
In contrast, installment loans are structured around a series of scheduled, fixed payments over a predetermined term, which can range from a few months to several years. This predictability allows freelancers to integrate the debt into their monthly budget, even if their income remains variable. Furthermore, installment loans generally offer lower Annual Percentage Rates (APRs) than payday loans, which have been documented to reach rates as high as 400% in certain jurisdictions. By spreading the cost of the loan over a longer duration, the immediate impact on the borrower’s monthly cash flow is significantly reduced.
Market Analysis: Leading Installment Loan Providers for the Self-Employed
As the demand for flexible credit grows, several lenders have emerged as dominant players in the sub-prime and fair-credit markets, each offering distinct advantages for those with irregular income.
1. CreditNinja: Accessibility and Speed
CreditNinja has positioned itself as a state-licensed online lender catering to borrowers who may not meet the stringent credit requirements of traditional banks. Since its inception in 2018, the company has served over 275,000 customers by utilizing technology-driven underwriting that prioritizes a borrower’s current ability to repay over their historical credit score. Their loans range from $300 to $5,000, with terms extending up to 24 months. The platform’s ability to provide same-day or next-day funding is a critical feature for freelancers facing immediate personal bill deadlines while waiting for a client’s wire transfer.
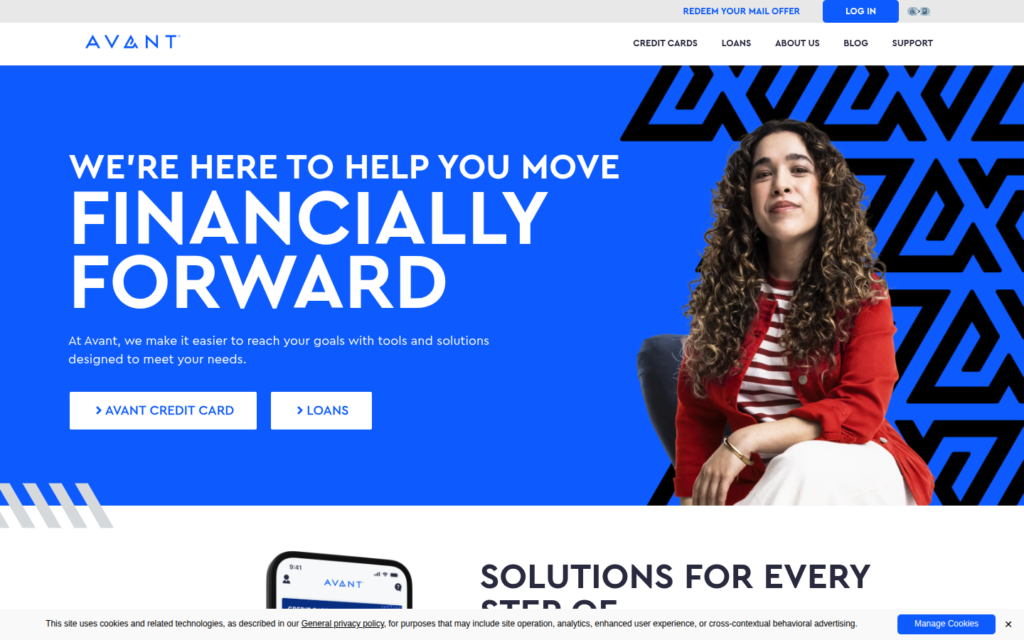
2. Avant: Mid-Range Credit Solutions
Avant targets the "fair-credit" segment, offering larger loan amounts ranging from $2,000 to $35,000. Their repayment terms are more extended, typically spanning 24 to 60 months. While Avant provides a significant liquidity injection, the presence of administrative fees and longer minimum terms suggests that this option is better suited for substantial, one-time expenses rather than minor cash-flow gaps.
3. Upstart: AI-Powered Underwriting
Upstart represents the shift toward artificial intelligence in the lending sector. By acting as a marketplace that connects borrowers with partner banks, Upstart utilizes non-traditional data—such as education and employment history—to assess creditworthiness. This is particularly beneficial for younger freelancers or those with "thin" credit files. Their loans go up to $75,000, though the limited choice between 36- or 60-month terms may be less flexible for those seeking short-term relief.
4. OneMain Financial: The Hybrid Model
OneMain Financial distinguishes itself through a network of physical branches combined with online services. For freelancers who prefer in-person consultation, OneMain offers a personalized approach to borrowing. Their loans range from $1,500 to $30,000. However, borrowers must be aware that some of their products may require collateral, which adds a layer of risk for those with fluctuating income.
5. Xact: Specialized Short-Term Support
Xact focuses on the lower end of the borrowing spectrum, with loans between $500 and $5,000. With terms up to 18 months and a lack of prepayment penalties, Xact provides a middle ground for freelancers who need more than a few hundred dollars but want to avoid a multi-year debt commitment.

Data-Driven Comparison of Lending Options
The following table summarizes the key metrics for the aforementioned lenders, highlighting the trade-offs between speed, amount, and long-term commitment.
| Lender | Loan Amount | Term Length | Funding Speed | Primary Advantage | Key Disadvantage |
|---|---|---|---|---|---|
| CreditNinja | $300–$5,000 | Up to 24 months | Same/Next Day | High accessibility for lower credit | Limited to $5,000 max |
| Avant | $2,000–$35,000 | 24–60 months | Next business day | Larger loan amounts | Administrative fees |
| Upstart | $1,000–$75,000 | 36 or 60 months | As fast as 1 day | AI-driven for thin credit | Limited term choices |
| OneMain | $1,500–$30,000 | 24–60 months | Same to 2 days | In-person support | Possible collateral required |
| Xact | $500–$5,000 | Up to 18 months | Next business day | Flexible schedules | State-specific availability |
Regulatory Context and Consumer Protections
The availability and cost of installment loans are heavily influenced by state-level regulations. Lenders must be licensed in each state where they operate, and many states have implemented interest rate caps to protect consumers from usurious practices. For instance, while some states allow APRs in the triple digits for small-dollar loans, others, like Illinois and California, have passed legislation to cap rates at 36% for most consumer loans. Freelancers are advised to review state-specific disclosures, as a loan offered to a resident of Texas may have vastly different terms than one offered to a resident of New York.
Implications for Long-Term Freelance Sustainability
While installment loans provide a necessary bridge during lean periods, financial analysts warn against the normalization of debt as a cash-flow management tool. The "debt-to-income" ratio remains a vital metric for personal financial health. If a freelancer finds themselves consistently utilizing installment loans to cover recurring monthly expenses, it may indicate a fundamental pricing issue or a need for a larger emergency fund.
Industry experts suggest a "Three-Tiered Approach" to managing the income gap:

- The Cash Reserve: Maintaining a minimum of three to six months of operating expenses in a high-yield savings account.
- The Line of Credit: Securing a business or personal line of credit during "flush" periods, which can be drawn upon and repaid as needed, often at lower rates than fixed installment loans.
- The Installment Loan: Utilizing fixed-term loans for specific, time-sensitive personal needs that cannot wait for the next client payment.
Conclusion: Bridging the Gap with Precision
The financial landscape for freelancers is evolving toward greater inclusion, but this inclusion comes with the responsibility of rigorous self-regulation. The predictable structure of installment loans offers a significant improvement over the volatility of payday lending, yet they are not a substitute for a sustainable business model. By carefully comparing lenders—evaluating not just the funding speed but also the total cost of credit and the flexibility of terms—independent workers can navigate the inevitable "lumps" of their income without compromising their long-term financial independence. As the freelance sector continues to grow, the ability to strategically manage credit will become as essential a skill as the professional services these workers provide.
