





The rise of the gig economy has fundamentally reshaped the American labor market, with an estimated 64 million Americans—approximately 38% of the workforce—performing freelance work in 2023. While this shift offers unprecedented flexibility, it has also introduced a pervasive financial challenge: the income-timing gap. For independent contractors, the primary obstacle is rarely a lack of total annual earnings, but rather the volatility of cash flow. A project may be completed and invoiced today, yet contractual "Net-30" or "Net-60" payment terms mean the actual funds may not arrive for two months. During this interim, fixed personal expenses, such as rent, utilities, and insurance, continue to accrue, creating a precarious mismatch between accounts receivable and immediate liabilities.
As this demographic grows, traditional banking institutions have often struggled to adapt their rigid underwriting criteria to accommodate variable income streams. In response, a specialized sector of the fintech lending market has emerged, offering personal installment loans as a strategic bridge for freelancers. Unlike the high-risk "payday" loans that have historically targeted low-income earners, modern installment loans provide a structured, predictable repayment model that aligns more closely with the cyclical nature of independent work.
The Structural Evolution of Short-Term Credit
To understand the current lending landscape, it is necessary to distinguish between the two primary forms of short-term credit available to those with irregular income: payday loans and installment loans.
Historically, freelancers facing a cash crunch often turned to payday loans. These products typically require a lump-sum repayment, including high interest and fees, to be paid in full by the borrower’s next "payday." For a freelancer, whose next influx of cash may be weeks away or split across multiple clients, the lump-sum requirement often leads to a "debt trap." If the borrower cannot pay the full amount plus interest at once, they are forced to roll the loan over into a new one, compounding fees.
In contrast, installment loans allow borrowers to receive a lump sum upfront and repay it through a series of scheduled, fixed monthly payments over a set term—ranging from a few months to several years. This structure provides a level of predictability that is vital for managing a variable budget. By spreading the cost of the loan over time, the monthly obligation becomes a manageable line item rather than a catastrophic financial event.

A Comparative Analysis of Leading Lending Platforms
The fintech sector has produced several key players that cater to the unique needs of the independent workforce. These platforms differ significantly in their underwriting methodologies, loan amounts, and speed of funding.
1. CreditNinja: Accessibility and Speed
CreditNinja has positioned itself as a state-licensed online lender focusing on transparency and speed. Their model is specifically designed for borrowers who may not have the "prime" credit scores required by traditional banks but possess a verifiable ability to repay based on current income.
- Loan Parameters: Amounts range from $300 to $5,000, with terms extending up to 24 months.
- Strategic Advantage: The platform utilizes technology-driven underwriting that looks beyond simple credit scores, considering a broader range of financial data. For a freelancer waiting on a specific invoice, the same-day or next-day funding capability is a critical feature for addressing time-sensitive personal emergencies.
2. Avant: The Fair-Credit Alternative
Avant targets the "middle-income" or "fair-credit" borrower, offering larger loan amounts that can be used for more significant financial restructuring or major unexpected expenses.
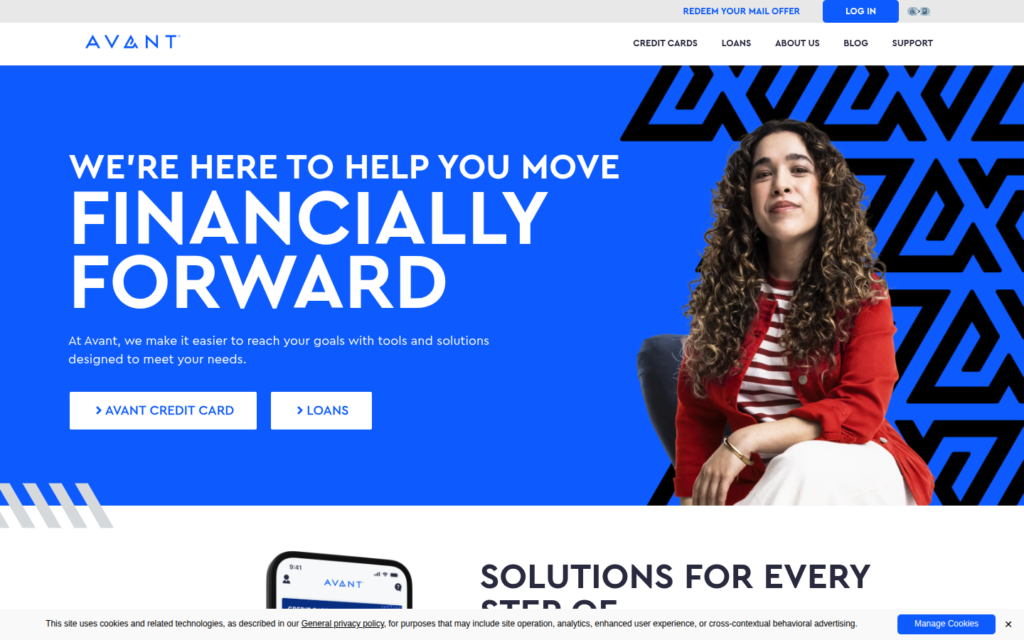
- Loan Parameters: Loans range from $2,000 to $35,000, with longer repayment windows of 24 to 60 months.
- Strategic Advantage: Avant provides a robust suite of financial-wellness resources. However, freelancers must account for administrative fees that are often deducted from the loan proceeds, meaning the amount deposited may be slightly less than the amount borrowed.
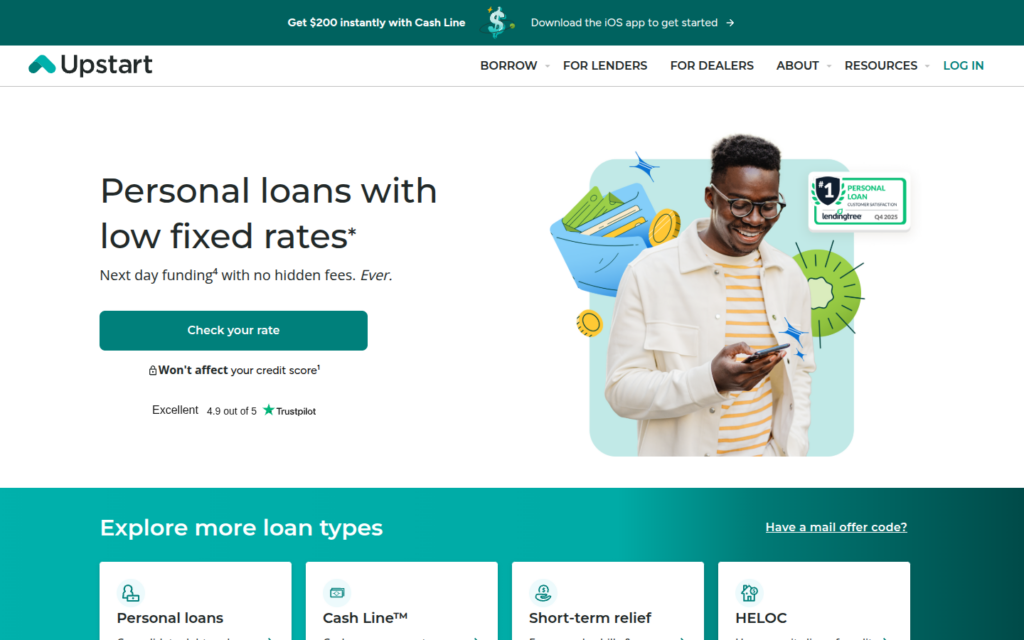
3. Upstart: AI-Driven Underwriting
Upstart represents the vanguard of AI-integrated lending. Rather than relying solely on FICO scores, Upstart’s proprietary algorithms consider variables such as educational background, work history, and even the specific field of study.
- Loan Parameters: Offers a wide range from $1,000 to $75,000.
- Strategic Advantage: For younger freelancers or those with "thin" credit files (individuals with little credit history), Upstart’s model provides a pathway to credit that traditional institutions might block. Their lack of a prepayment penalty is particularly beneficial for freelancers who may want to settle their debt early after receiving a large project bonus.
4. OneMain Financial: The Hybrid Model
OneMain Financial distinguishes itself by maintaining a network of physical branches alongside its digital platform. This provides a "human element" that many digital-only lenders lack.
- Loan Parameters: $1,500 to $30,000 with terms up to five years.
- Strategic Advantage: The ability to speak with a loan officer in person can be advantageous for freelancers with complex financial situations that are difficult to explain to an automated algorithm. They also offer secured loan options, which can lower interest rates if the borrower has collateral.
5. Xact: Small-Scale Agility
Xact focuses on the lower end of the borrowing spectrum, catering to those who need smaller amounts to cover minor gaps without committing to a multi-year debt cycle.
- Loan Parameters: $500 to $5,000 with terms up to 18 months.
- Strategic Advantage: Xact offers flexible payment frequencies, including biweekly or semimonthly options. This allows a freelancer to align their loan payments with their specific billing cycles.
The Macroeconomic Context: The Cost of Late Payments
The necessity for these loan products is driven by a systemic issue in the business world: the "late payment culture." According to a 2022 study by Independent Collector, approximately 74% of freelancers reported experiencing late payments at least once in their careers. On a global scale, it is estimated that $3 trillion in payments are tied up in accounts receivable at any given time.
This delay in capital movement acts as a hidden tax on the self-employed. When a freelancer is forced to borrow to cover the gap created by a client’s late payment, the interest on that loan essentially reduces their net profit for the project. Industry analysts suggest that until federal or state "Freelance Isn’t Free" acts—like those passed in New York City and Illinois—become more widespread and enforceable, the reliance on bridge financing will continue to grow.
Chronology of a Financial Gap: When to Borrow
Financial experts suggest a specific chronology for assessing the need for an installment loan:
- The Invoice Stage: A project is delivered. The freelancer should immediately track the expected payment date.
- The Buffer Assessment: If the payment date falls after major bills are due, the freelancer should first look to an emergency fund (ideally 3–6 months of expenses).
- The Negotiation Stage: Contacting creditors to request a grace period or payment plan is the next logical step.
- The Borrowing Stage: If a gap remains, an installment loan should be sought. The goal is to secure the loan before a missed payment affects the borrower’s credit score, which would make borrowing more expensive in the future.
Risk Analysis and Long-Term Implications
While installment loans are a superior alternative to payday lending, they are not without risk. The primary danger for the freelancer is "payment fatigue"—the accumulation of multiple monthly obligations that consume an increasing percentage of their variable income.
Data suggests that the average APR for personal loans can vary wildly based on creditworthiness and state regulations, sometimes ranging from 6% to 36% or higher for subprime products. Freelancers must also be wary of origination fees and the impact of "hard" credit inquiries on their credit reports.
Furthermore, repeated use of installment loans to solve recurring cash flow issues may indicate a structural problem with a freelancer’s pricing or client base. Analysts recommend that if a freelancer finds themselves borrowing more than twice a year to cover basic living expenses, they should consider a "Line of Credit" (LOC). Unlike a loan, an LOC provides a revolving pool of funds that can be drawn upon and repaid as needed, often with lower interest costs for short-term usage.

Conclusion: The Future of Freelance Finance
The integration of AI in underwriting and the expansion of niche fintech lenders have provided a vital safety net for the modern independent worker. As the gig economy continues to mature, the financial sector is beginning to recognize that "irregular income" does not equate to "unreliable income."
Installment loans, when used judiciously, serve as a tool for financial stabilization, allowing freelancers to maintain their personal credit health and focus on business growth rather than immediate survival. However, the ultimate solution to the freelance income gap lies in a combination of better legislative protections for payment terms, increased financial literacy among independent contractors, and the continued evolution of lending products that respect the unique rhythms of the self-employed life. For now, bridging the gap without the guesswork requires a disciplined approach to comparing terms, understanding the total cost of capital, and maintaining a clear-eyed view of future earnings.
