
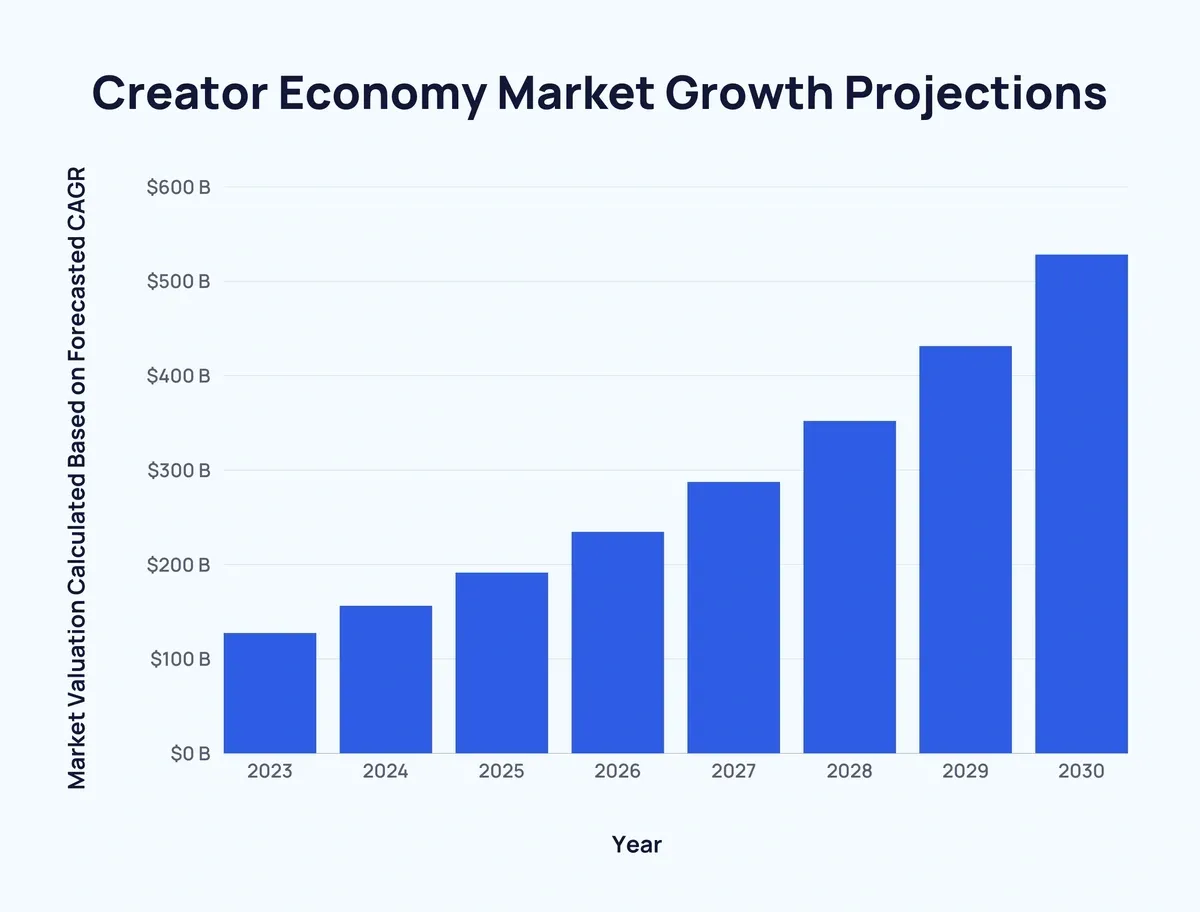
The global creator economy has officially transitioned from a nascent digital subculture into a formidable $100 billion market sector as of the first quarter of 2026, marking a pivotal era where individual content production rivals traditional media conglomerates in influence and revenue. As the industry enters this mature phase, the landscape is characterized by a strategic shift away from platform dependency toward diversified business models, emphasizing long-form content, niche community engagement, and multi-channel monetization. Data from recent industry reports indicates that the "creator-middle class" is expanding, with a significant increase in the number of individuals generating full-time income through a combination of subscriptions, direct-to-consumer commerce, and intellectual property licensing.
The Historical Trajectory of the Creator Economy (2020–2026)
To understand the current state of the market in 2026, it is essential to trace the chronological development of digital creation over the past half-decade. In the early 2020s, the industry was primarily defined by the "Gold Rush" of short-form video, led by platforms like TikTok and Instagram Reels. This period focused heavily on viral growth and the pursuit of massive follower counts, which were then leveraged for high-value brand sponsorships.
By 2023 and 2024, the market began to experience "influencer fatigue," leading to a correction where engagement rates and audience trust became more valuable than raw reach. This period saw the rise of creator-focused infrastructure, including platforms like Ghost and Shopify, which allowed creators to own their audience data and storefronts. Entering 2025, the focus shifted toward "sustainability," as creators realized that reliance on algorithmic discovery was a precarious business model.
As of January 2026, the industry has reached a state of professionalization. The "creator-as-CEO" model is now the standard, with successful digital entrepreneurs employing small teams to manage production, community moderation, and diversified revenue streams. The volatility of the early 2020s has been replaced by a more structured environment where strategic planning and long-term brand equity are prioritized over temporary viral trends.
Core Market Trends Defining the 2026 Landscape
Analysis from NeoReach and other market research firms identifies six primary trends that are currently dictating the flow of capital and attention within the creator economy. These trends reflect a broader move toward economic stability and deeper audience connections.
Revenue Diversification and the Decline of Sponsorship Dependency
Creators are increasingly insulating themselves from the fluctuations of the advertising market. While brand deals remain a component of income, the 2026 model prioritizes "owned" revenue. This includes tiered subscription models, digital products, and private memberships. By reducing their dependence on one-off sponsorships, creators are achieving more predictable cash flows and greater creative autonomy.
The Resurgence of Long-Form Content
While short-form video remains a powerful discovery tool, long-form content—including podcasts, newsletters, and documentary-style YouTube videos—is seeing the highest gains in trust and audience retention. Industry data suggests that audiences in 2026 are seeking depth and expertise, viewing long-form creators as authoritative figures in their respective niches. This shift has prompted a "re-centralization" of content, where short clips are used as marketing for comprehensive, high-value long-form assets.
Micro-Community Optimization
The 2026 market has effectively debunked the myth that "bigger is always better." Creators with smaller, highly engaged communities are currently outperforming mass-market influencers in conversion rates and brand loyalty. This "micro-community" trend is driven by the desire for authentic interaction. Platforms that facilitate two-way communication and interactive streaming have become the preferred hubs for these high-value cohorts.
Traditional Media Convergence
The boundary between "digital creator" and "traditional celebrity" has become nearly indistinguishable. YouTube viewership now rivals traditional television networks in several key demographics, leading to a surge in creators crossing over into film, mainstream broadcasting, and professional sports commentary. This convergence has opened new avenues for creators to license their content to streaming giants and cable networks, further legitimizing the profession.
Taxonomic Classification of the 2026 Digital Creator
As the industry has matured, specific archetypes have emerged, each requiring a distinct strategic approach to achieve commercial viability. According to Shopify’s analysis of the digital workforce, creators generally fall into six categories based on their skill sets and audience relationship.
The Virtuoso
Virtuosos are subject-matter experts who leverage their professional backgrounds in fields such as finance, healthcare, or the culinary arts. Their content is primarily educational, focusing on tutorials, data analysis, and problem-solving. For the Virtuoso, the primary product is their expertise, often monetized through high-ticket courses or consulting.
The Bellwether
Bellwethers function as cultural curators and trendsetters. Often found on visually-driven platforms like Instagram or Pinterest, their value lies in their taste and their ability to forecast aesthetic shifts. They are the primary beneficiaries of the "curation economy," earning revenue through affiliate partnerships and brand ambassadorships.
The Performer
Performers excel in the traditional entertainment arts, including acting, comedy, and music. Their success in 2026 is predicated on their ability to adapt these skills to digital formats, using platforms like TikTok and YouTube to build a personal brand that can eventually transition into live tours or mainstream media contracts.
The Technophile
This category encompasses gamers, gadget reviewers, and software enthusiasts. Technophiles rely heavily on live-streaming platforms like Twitch and specialized tech channels. Their monetization strategies are often the most diverse, including ad revenue, hardware partnerships, and "e-sports" style competitions.
The Maker and the Iconoclast
Makers focus on physical craftsmanship, such as woodworking or textile design, while Iconoclasts are independent artists like photographers and graphic designers. Both groups utilize the creator economy as a storefront for their physical or digital goods, using social media as a top-of-funnel marketing tool to drive traffic to independent e-commerce sites.
Industry Responses and Infrastructure Support
The rapid professionalization of the creator sector has prompted significant responses from technology providers and financial institutions. Platforms like Ghost have expanded their offerings to include sophisticated CRM (Customer Relationship Management) tools, allowing creators to segment their audiences and deliver personalized content.
Kendall Breitman, a lead at Riverside, emphasizes that the "barrier to entry" has evolved. While it is easier than ever to start, the technical requirements for success have increased. Professional-grade audio and video equipment, once reserved for television studios, are now standard for top-tier creators. This has created a secondary market for creator-specific hardware and software, further contributing to the $100 billion ecosystem.
Furthermore, financial institutions are beginning to recognize creator revenue as "stable income" for the purposes of business loans and mortgages. This institutional recognition is a landmark development in the 2026 economy, signaling that digital content creation is no longer viewed as a precarious "gig" but as a legitimate entrepreneurial career path.
Strategic Framework for Growth in the Current Climate
For those entering the market or looking to scale in 2026, industry experts suggest a 12-week foundational plan centered on "content-market fit." This involves a rigorous assessment of the creator’s unique value proposition followed by a strategic rollout across multiple platforms.
The first phase focuses on "Discovery and Definition," where the creator identifies their niche and selects the primary medium (text, audio, or video) that best suits their strengths. The second phase involves "Infrastructure Building," which includes setting up a self-owned platform (newsletter or website) to ensure audience ownership. The final phase is "Monetization and Community Integration," where the creator introduces value-added services or products to their most loyal followers.
Broader Economic and Social Implications
The rise of the creator economy in 2026 has profound implications for the broader global economy. The democratization of content production has challenged the monopoly of traditional media houses, leading to a more fragmented but diverse information landscape. This shift has also decentralized economic opportunity, allowing individuals in geographically remote areas to access global markets.
However, this evolution also presents challenges. The "ownership" of the relationship between creator and fan is a point of ongoing legal and ethical debate. As investors shift their interest toward creator-first platforms that prioritize data portability and ownership, the dominant social media giants are being forced to reform their creator-payout structures to prevent an exodus of talent.
In conclusion, the creator economy of 2026 is a sophisticated, multi-faceted industry that rewards strategy, consistency, and authentic community building. The transition from a viral-centric model to a sustainable business-centric model has provided a blueprint for the next generation of digital entrepreneurs. As the lines between media, commerce, and community continue to blur, the creators who prioritize ownership and long-term audience trust are positioned to lead the global economic narrative for the remainder of the decade.
