
The global freelance economy has undergone a seismic shift as it enters the mid-2020s, with projections from the World Economic Forum and various labor organizations suggesting that independent contractors now constitute nearly 45% of the total workforce in developed economies. As this sector matures, the logistical challenges of cross-border commerce, currency volatility, and cash flow management have moved to the forefront of industry discourse. This evolution provides the backdrop for the upcoming 10X Your Freelancing Summit, scheduled for August 25-27, 2026, where thousands of independent professionals will gather virtually to address the critical infrastructure of the gig economy. Central to these discussions is the selection of payment processing platforms, a choice that has evolved from a matter of convenience to a strategic business decision capable of impacting a freelancer’s annual bottom line by as much as 5% to 8% in gross revenue.

The Evolution of Freelance Payments: 2020–2026
The trajectory of freelance payment systems over the last six years reflects a broader trend toward the "consumerization" of enterprise-grade financial tools. In the early 2020s, freelancers often relied on personal peer-to-peer apps or high-fee legacy systems.
By 2026, the market has bifurcated into specialized ecosystems that prioritize either high-volume international transfers, seamless B2B invoicing, or immediate consumer-facing transactions. Industry analysts note that the "friction" associated with traditional banking—characterized by multi-day settlement periods and opaque fee structures—is being systematically dismantled by fintech innovators.

The upcoming 10X Your Freelancing Summit highlights a critical transition point. As freelancers move away from "side-hustle" mentalities toward formal micro-business structures, the demand for professionalized invoicing, automated tax withholding, and real-time cash flow analytics has reached an all-time high. The following analysis examines the ten primary payment applications dominating the landscape in 2026, categorized by their utility, cost-efficiency, and market positioning.
Strategic Market Leaders in B2B and Cash Flow Management
1. Melio: The Business Operations Anchor
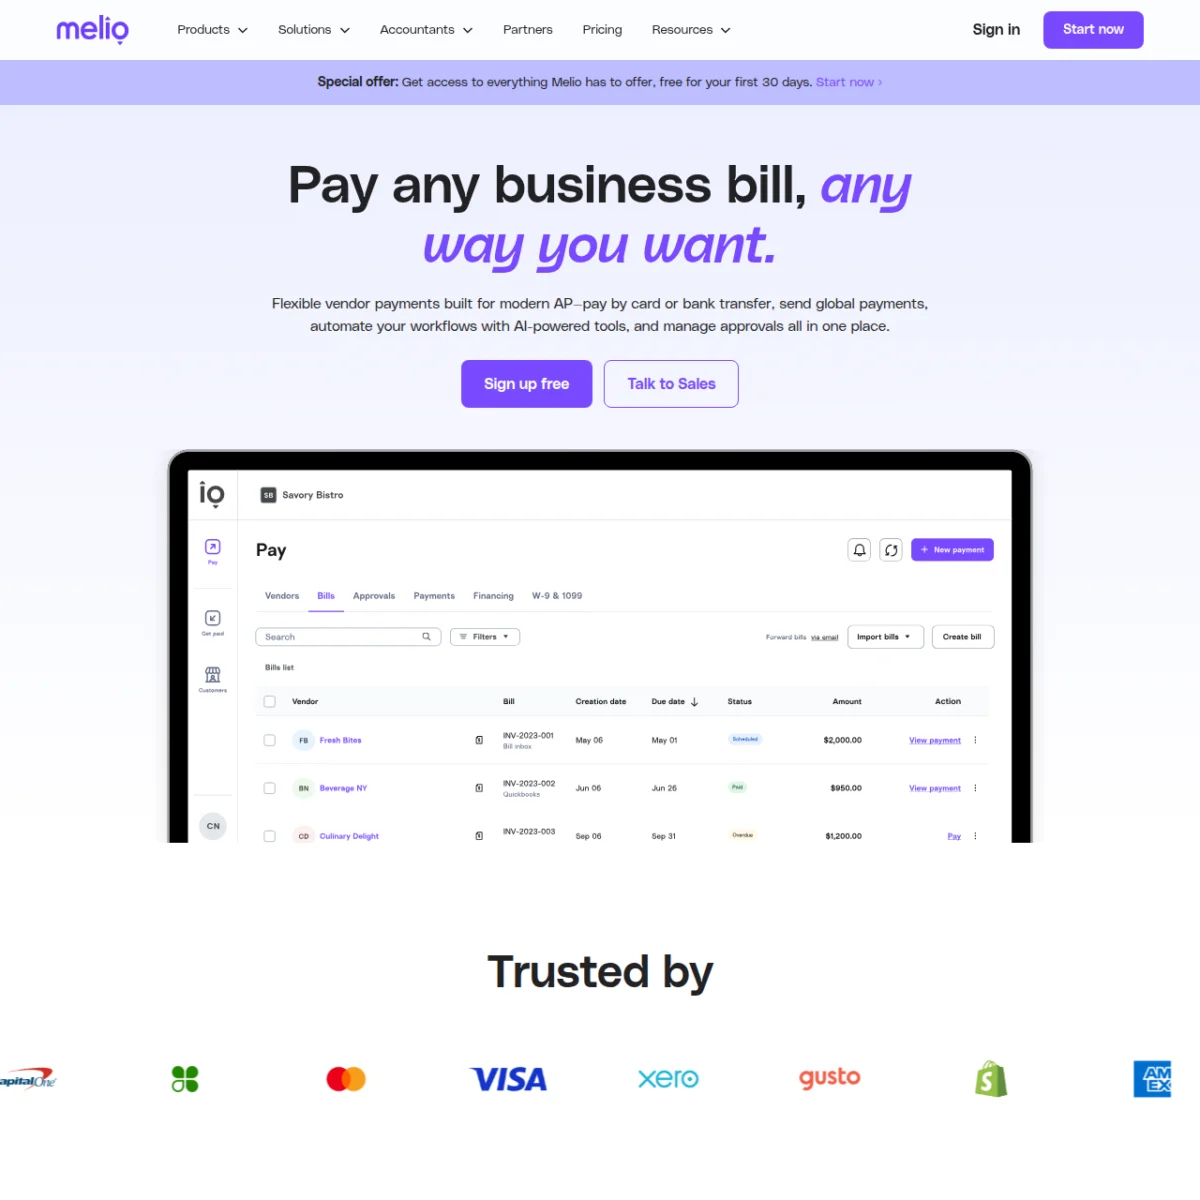
Melio has emerged as the premier choice for freelancers operating under formal business entities, such as LLCs or S-Corps. Unlike traditional payment processors, Melio functions as a comprehensive accounts payable and receivable dashboard. Its primary value proposition lies in its ability to synchronize with accounting software like QuickBooks and Xero, providing a unified view of a freelancer’s financial health.
For the modern freelancer, Melio’s support for free ACH bank transfers addresses the "fee fatigue" prevalent in the industry. By allowing clients to pay via credit card while the freelancer receives funds via ACH, it bridges the gap between client convenience and freelancer profitability. Market data suggests that freelancers utilizing integrated cash flow tools like Melio report a 20% reduction in late payments due to automated reminder systems and streamlined interfaces.
2. Stripe: The Global Standard for Technical Integration
Stripe remains the infrastructure of choice for high-end consultants, developers, and digital agencies. In 2026, its invoicing suite has become highly sophisticated, offering features such as "smart retries" for failed subscription payments and localized payment methods for over 135 currencies. Stripe’s 2.9% + $0.30 fee structure remains the industry benchmark for credit card processing, though its true value lies in its extensibility through APIs and shareable payment links.

3. Wise: Mitigating Currency Volatility
With the rise of the "digital nomad" and the globalization of talent, Wise (formerly TransferWise) has become an essential component of the freelance toolkit. The platform’s adherence to the mid-market exchange rate—the same rate used by major banks to trade between themselves—offers a transparent alternative to the hidden markups found in legacy banking systems. For freelancers billing in USD while living in lower-cost-of-living regions, or vice versa, the savings provided by Wise often exceed several thousand dollars annually compared to traditional wire transfers.
Legacy Platforms and Marketplace Integration
4. PayPal: The Ubiquitous Safety Net
Despite growing competition and a reputation for higher-than-average fees, PayPal maintains a dominant market share due to its universal brand recognition. In 2026, PayPal is often utilized as a secondary or "backup" payment method. Its primary strength is trust; many risk-averse clients are more comfortable sending large sums through a platform with robust dispute resolution mechanisms. However, with fees for invoiced payments often exceeding 3.49%, many seasoned professionals are increasingly routing primary transactions through lower-cost alternatives.

5. Payoneer: The Marketplace Specialist
Payoneer continues to hold a strategic advantage for freelancers who derive the majority of their income from platforms such as Upwork, Fiverr, or Toptal. By providing "local" bank account details in multiple jurisdictions (including the US, EU, UK, and Japan), Payoneer allows freelancers to receive marketplace payouts as if they were local residents, significantly reducing international transfer friction.
Consumer-Facing and Hybrid Payment Solutions
6. Square: Bridging the Physical-Digital Divide
Square has successfully transitioned from a hardware-centric company to a versatile software provider. It remains the top choice for freelancers whose work involves an in-person component, such as event photographers, on-site consultants, or coaches. The ability to accept a physical card via a mobile reader while maintaining a professional online invoicing presence provides a level of flexibility that few other platforms can match.
7. Zelle: The Zero-Fee Domestic Alternative
Within the United States, Zelle has become a favored tool for established, trust-based client relationships. Because it is integrated directly into the infrastructure of major American banks, it facilitates near-instantaneous transfers without transaction fees. Its primary drawback remains its lack of professional invoicing features and its limitation to domestic transactions, making it a "utility" rather than a comprehensive business solution.
8. Venmo Business, 9. Revolut Business, and 10. Cash App Business
These three platforms represent the "consumerization" of freelance payments. Venmo and Cash App Business are tailored toward freelancers serving individual consumers (B2C), where the client prefers the ease of a social media-style interface. Revolut Business, conversely, caters to the ultra-mobile professional, offering multi-currency accounts and corporate cards that appeal to those working across the European and UK markets.

Comparative Data: The Real Cost of Payment Processing
To understand the financial impact of these choices, consider a freelancer earning $75,000 annually. If 100% of their payments are processed via a platform with a 3.5% fee (like certain PayPal tiers), they will incur $2,625 in annual costs. By shifting just 50% of those payments to a free ACH system like Melio or a zero-fee domestic transfer like Zelle, the freelancer can recover over $1,300—roughly the cost of a high-end laptop or a month’s worth of health insurance premiums.
Furthermore, speed of transfer has become a critical metric. In 2026, the standard for "fast" payments has shifted from 3–5 business days to under 24 hours. Platforms like Melio and Stripe have introduced expedited settlement options, recognizing that for an independent professional, liquidity is often more important than the absolute lowest fee.

Industry Response and Regulatory Context
The shift toward these digital payment ecosystems has caught the attention of global regulatory bodies. The IRS in the United States and similar tax authorities in the EU have implemented stricter reporting requirements for payment processors (such as the 1099-K thresholds). Consequently, the top-tier apps in 2026 have invested heavily in "tax-ready" reporting features, helping freelancers navigate increasingly complex compliance landscapes.
Fintech analyst Sarah Jenkins of Global Labor Trends notes, "The payment app is no longer just a digital wallet; it is the freelancer’s de facto CFO. In 2026, the competitive advantage goes to the professional who treats their payment stack with the same rigor that a Fortune 500 company treats its treasury department."

Implications for the Future of Independent Work
As the 10X Your Freelancing Summit approaches, the consensus among industry leaders is that the "platformization" of payments will continue. We are likely to see further integration between payment apps and broader business services, including insurance, retirement planning, and micro-lending based on invoice history.
For the individual freelancer, the directive is clear: a multi-platform strategy is the most resilient approach. By utilizing Melio for domestic B2B work, Wise for international contracts, and keeping a legacy option like PayPal for client convenience, the modern freelancer can optimize for both professionalism and profitability. The right systems do more than move money; they validate the freelancer’s status as a legitimate business entity in an increasingly crowded global marketplace. Getting paid is no longer just the end of a project—it is a sophisticated operational process that defines the success of the modern independent career.
