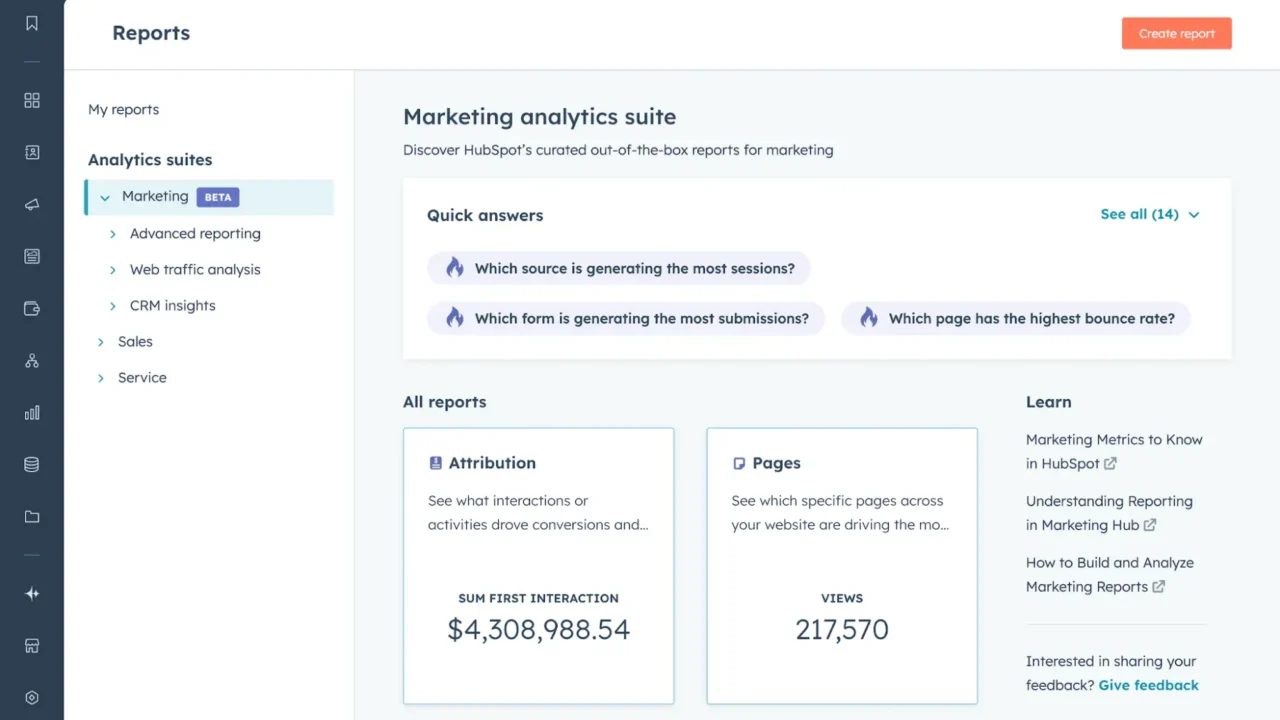

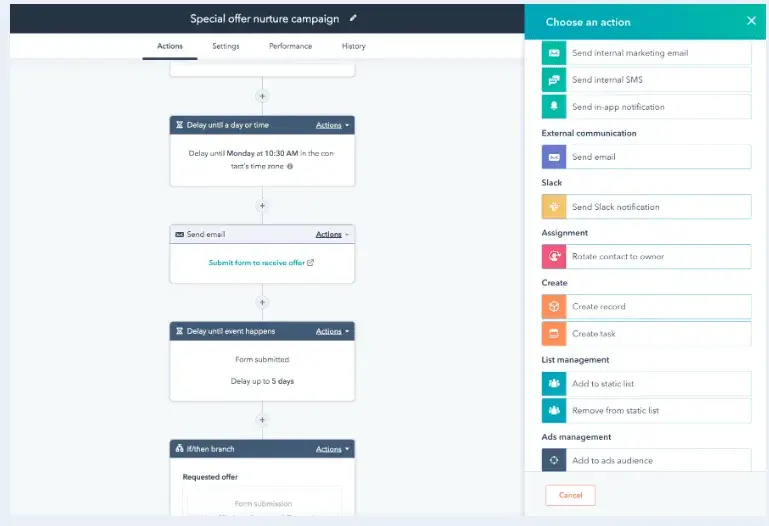
The insurance industry, traditionally characterized by its reliance on legacy systems and manual record-keeping, is currently undergoing a significant digital transformation centered on the adoption of specialized Customer Relationship Management (CRM) platforms. In an era where consumer expectations are shaped by seamless digital experiences in retail and banking, insurance agencies are increasingly recognizing that their primary competitive advantage lies in the depth and efficiency of their client relationships. A modern CRM for insurance companies is no longer merely a digital Rolodex; it has become a sophisticated engine for managing the entire policy lifecycle, from initial lead generation and nurturing to customer service, complex claims support, and policy renewals.
The Landscape of Digital Transformation in Insurance
Historically, the insurance sector has been hampered by fragmented data silos. For decades, agents relied on physical filing cabinets or rudimentary spreadsheet systems to track client interactions. The emergence of Agency Management Systems (AMS) in the late 20th century provided a framework for policy administration, but these tools often lacked the front-end agility required for modern sales and marketing. As we move toward 2026, the integration of CRM technology represents a shift from a transaction-centric model to a relationship-centric one.
Industry data underscores the urgency of this transition. According to recent lead-response studies, insurance leads contacted within one hour are 60 times more likely to qualify than those contacted 24 hours later. In a market where price transparency is high, response speed and personalized engagement have become the primary differentiators for successful agencies.
A Chronology of Technological Integration
The adoption of insurance technology has followed a distinct timeline of professionalization. In the early 2000s, the "Agent Portal" became the standard, allowing producers to quote and bind policies directly with carriers. However, these portals remained isolated from the agent’s internal records. By 2010, the AMS became the "source of truth" for policy documents and commission accounting.
The current decade marks the "CRM Era," where agencies are layering specialized communication tools over their administrative databases. This evolution allows for a unified view of the customer, ensuring that a service representative answering a call in 2025 has the same historical context as the producer who sold the policy five years prior. This continuity is vital for maintaining trust and reducing the friction that often leads to policyholder churn.

Distinguishing the Core Systems: CRM, AMS, and Agent Portals
To understand the strategic value of a CRM, it is essential to distinguish it from other critical software used by insurance teams. While these systems often overlap, they serve distinct functions within an agency’s operations:
- Customer Relationship Management (CRM): Primarily utilized by sales and marketing teams, the CRM focuses on the pipeline. Its key functions include lead tracking, automated email sequences, sales forecasting, and social media integration. It is designed to turn prospects into policyholders.
- Agency Management System (AMS): Used by operations and service staff, the AMS is the backbone of policy administration. It handles the "back-office" functions such as policy records, commission tracking, accounting, and carrier downloads via ACORD standards.
- Agent Portals: These are carrier-provided platforms used by producers to compare rates, submit applications, and issue policies. They are essential for the "bind" phase of the sales process but do not track the long-term relationship history of the client.
Strategic Benefits and Performance Data
The implementation of a dedicated insurance CRM yields measurable improvements in key performance indicators (KPIs). One of the most significant impacts is seen in retention rates. In the property and casualty (P&C) sector, the average retention rate hovers around 84%. However, agencies utilizing automated renewal workflows—which trigger alerts 60 to 90 days before a policy expires—report retention rates exceeding 90%.
For example, the insurtech firm YuLife utilized CRM automation to trigger personalized outreach sequences, ultimately achieving a 98% customer retention rate. This performance is approximately 20% above the industry average, demonstrating the financial impact of proactive, data-driven engagement.
Furthermore, CRMs facilitate systematic cross-selling. By analyzing existing policy data, a CRM can automatically flag a client who holds an auto policy but lacks homeowners or umbrella coverage. This automated identification removes the need for manual account reviews, allowing agents to offer relevant products at the moment of highest intent.
Essential Features for the Modern Insurance Agency
As the industry looks toward 2026, several "must-have" features have emerged that distinguish top-tier insurance CRMs from generic business tools:
Insurance-Native Data Fields
Generic CRMs require extensive customization to understand the nuances of the insurance business. A specialized platform comes pre-configured with fields for policy numbers, coverage limits, deductibles, beneficiaries, and carrier-specific information. This allows for immediate deployment without the need for expensive consultants.
Carrier and AMS Integration
The utility of a CRM is halved if it cannot communicate with the agency’s AMS or carrier tools. Modern platforms utilize APIs to ensure that data flows seamlessly between systems, reducing the need for manual data entry and minimizing the risk of human error.
Automated Lead Routing and Follow-up
In an industry where the first responder often wins the business, automated lead routing ensures that new inquiries are instantly assigned to the most qualified producer. Furthermore, since insurance sales often require a minimum of seven touchpoints to close, automated follow-up sequences ensure that prospects remain engaged over weeks or months without requiring constant manual intervention from the agent.
AI-Powered Analytics and Outreach
Artificial Intelligence is increasingly integrated into insurance CRMs to provide predictive scoring. These tools can analyze historical data to identify which leads are most likely to close and which current clients are at high risk of cancellation. Additionally, AI agents can now summarize long email chains and draft personalized renewal notices, significantly reducing the administrative burden on staff.
Comparative Analysis of Leading Platforms
The 2026 market features five dominant players, each catering to different agency profiles:
- HubSpot CRM: Highly rated for its user interface and scalability, HubSpot is increasingly popular among growing agencies. It offers a "freemium" model that allows small firms to start with basic tools and add sophisticated marketing and service hubs as they expand. Its strength lies in its unified customer record that bridges the gap between sales and service.
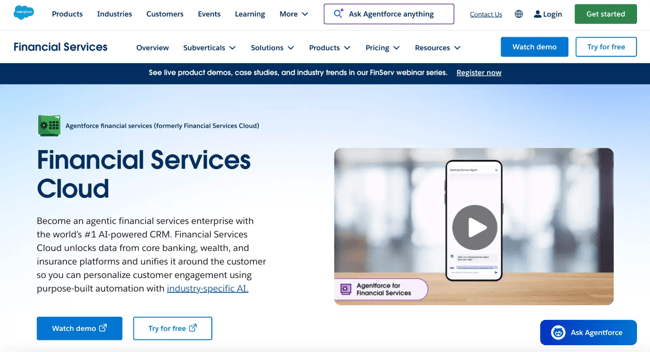
- Agentforce Financial Services (Salesforce): Formerly known as Salesforce Financial Services Cloud, this platform is the industry standard for large enterprises and global insurers. It offers unparalleled customization and a prebuilt financial data model, though it often requires significant investment in implementation.
- Applied Epic: A dominant force for mid-to-large independent agencies, Applied Epic combines AMS and CRM capabilities. It is particularly strong in managing complex commercial lines and benefits packages across multiple locations.
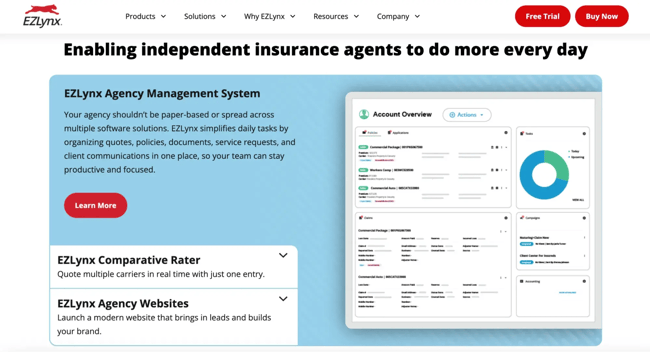
- EZLynx: Built specifically for independent P&C agencies, EZLynx integrates a comparative rater with its CRM. It is prized for its "all-in-one" approach, though it may lack the depth of marketing automation found in more generalized CRMs.
- Vertafore AMS360: A staple for established agencies, Vertafore offers a robust ecosystem of products. Its recent focus on AI-powered email agents and automated reconciliation has made it a leader in operational efficiency.
Implementation Framework and Industry Implications
The transition to a new CRM is a high-stakes endeavor. Industry experts recommend a six-step framework for successful adoption: identifying specific pain points, gathering feedback from all user levels, shortlisting features, comparing total cost of ownership (including onboarding fees), requesting demos with actual agency data, and appointing a "CRM champion" to lead the internal rollout.
The implications of this technological shift extend beyond simple efficiency. As CJ Hutsenpiller of Hutsenpiller Insurance noted, agencies remaining on legacy systems risk not only losing clients to tech-forward competitors but also devaluing their business. In the current M&A environment, the value of an insurance agency is increasingly tied to the quality and organization of its digital data.
Future Outlook: The Relationship-Driven Agency
As we move further into the decade, the role of the insurance agent is evolving from a policy provider to a risk advisor. This shift is made possible by CRM systems that handle the "heavy lifting" of administration and routine communication. By leveraging data to provide proactive advice—such as alerting a client to a potential coverage gap following a major life event—agents can solidify their role as trusted partners.
In conclusion, the adoption of a specialized CRM is no longer an optional upgrade for insurance companies; it is a fundamental requirement for survival in a digital-first economy. Those who successfully integrate these tools will benefit from higher retention, increased cross-sell opportunities, and a more resilient, data-driven business model. The future of insurance belongs to those who can marry the traditional values of relationship-based service with the speed and precision of modern technology.
