
The expansion of the global gig economy has fundamentally altered the traditional landscape of personal finance, introducing a persistent challenge known as income volatility. For the estimated 60 million independent workers in the United States alone, the primary financial hurdle is often not a lack of total annual earnings, but rather the misalignment of income timing. In a professional environment where project completion and invoicing may precede actual payment by 30 to 60 days, freelancers frequently encounter "cash flow gaps." During these periods, fixed personal obligations—such as rent, utilities, and insurance—continue to accrue regardless of the status of outstanding accounts receivable. To bridge these gaps, an increasing number of independent contractors are turning to personal installment loans as a more structured and predictable alternative to high-interest predatory lending products.
The fundamental mismatch between work performed and liquidity received does not necessarily indicate a failing business model; rather, it reflects the inherent nature of contract-based labor. Financial analysts observe that while a loan can serve as a temporary bridge for specific personal expenses during lean intervals, the long-term health of a freelance enterprise depends on borrowing remaining an occasional strategic tool rather than a habitual management tactic. The shift toward installment-based borrowing represents a maturing of the freelance financial sector, moving away from the "lump-sum" trap of traditional payday loans toward more manageable, amortized repayment schedules.
The Structural Evolution of Small-Dollar Lending for Independent Workers
The distinction between installment loans and payday loans is critical for the self-employed demographic. Traditional payday loans typically require a full lump-sum repayment, including interest and fees, to be deducted from the borrower’s next direct deposit. For a freelancer without a guaranteed "payday," this requirement can trigger a cycle of debt, as the borrower may lack the full amount when the loan comes due, necessitating a costly "rollover."
In contrast, personal installment loans utilize a fixed repayment structure. By dividing the total amount owed into predictable monthly payments over a defined term—ranging from a few months to several years—these loans allow freelancers to integrate debt service into their variable monthly budgets. This transparency is particularly valuable for those attending industry events like the upcoming 10X Your Freelancing Summit, scheduled for August 25-27, 2026, where thousands of independent professionals gather virtually to discuss scaling strategies and financial sustainability. As the freelance sector grows, the demand for financial products that accommodate non-traditional income streams has led to the rise of specialized online lenders.
Comparative Analysis of Leading Installment Loan Providers
Lending institutions have begun to refine their underwriting models to better serve the "thin-file" or variable-income borrower. While traditional banks often rely heavily on W-2 documentation, modern fintech firms utilize alternative data to assess creditworthiness. The following five lenders represent the current spectrum of installment loan options available to the freelance community.

1. CreditNinja: High-Speed Accessibility for Lower Credit Profiles
CreditNinja has positioned itself as a state-licensed online lender catering to borrowers who may not qualify for prime bank rates. Offering loan amounts between $300 and $5,000, CreditNinja emphasizes transparency and speed, with funding often available on the same or next business day.
Unlike payday loans, which can carry Annual Percentage Rates (APRs) exceeding 400%, or title loans that require vehicle collateral, CreditNinja’s products are structured as unsecured installment loans with terms extending up to 24 months. Their technology-driven underwriting platform considers the applicant’s overall ability to repay rather than focusing solely on a legacy credit score. Since its inception in 2018, the company has served over 275,000 customers across more than 30 states, reflecting a significant demand for accessible, mid-range credit.
2. Avant: Specialized Solutions for Fair-Credit Borrowers
Avant targets a slightly higher credit tier, primarily focusing on "fair-credit" individuals who require larger capital infusions. Their loan products range from $2,000 to $35,000, with repayment terms spanning 24 to 60 months. This longer duration allows for lower monthly payments, which can be advantageous during prolonged contract droughts. However, borrowers must account for administrative fees that may be deducted from the initial loan disbursement. Avant also integrates financial wellness resources into its platform, aiming to help borrowers improve their long-term credit health while managing current liabilities.
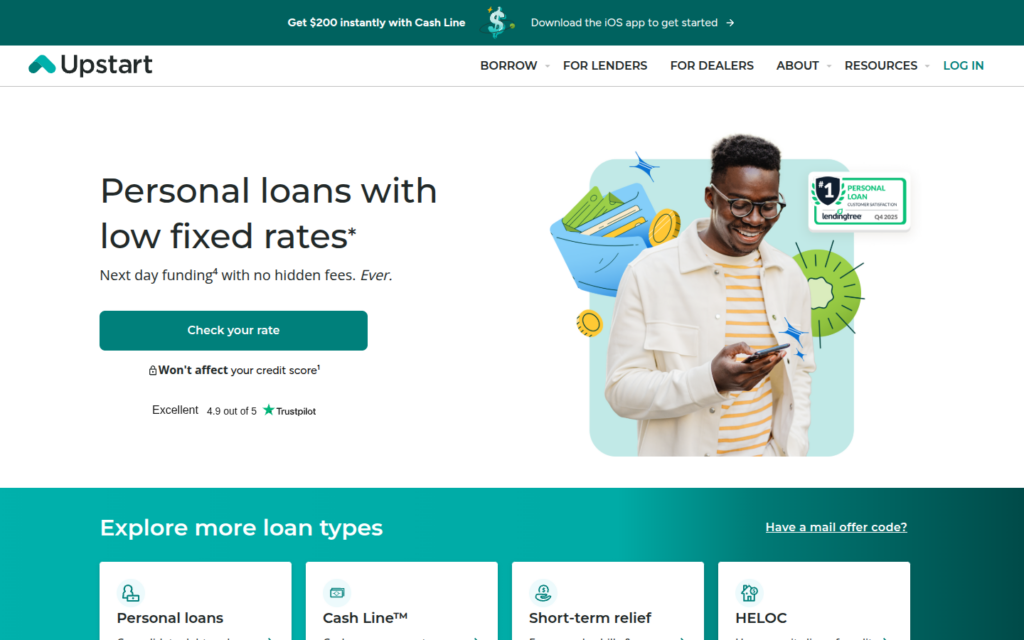
3. Upstart: The Role of Artificial Intelligence in Underwriting
Upstart operates as an AI-powered lending marketplace, connecting freelancers with a network of partner financial institutions. Their innovative approach is particularly relevant for younger freelancers or those with "thin" credit files. By using machine learning to analyze non-traditional variables—such as education and employment history—Upstart can often provide more favorable terms than lenders relying on antiquated FICO models. They offer loans from $1,000 to $75,000, though they maintain a rigid choice between 36-month and 60-month terms, which may be longer than some freelancers require for a temporary cash-flow fix.
4. OneMain Financial: The Hybrid Model of Digital and Physical Support
OneMain Financial distinguishes itself by maintaining a network of physical branches alongside its digital presence. For freelancers who prefer in-person consultation, this model offers a level of personalized service rarely found in the fintech space. Loan amounts typically range from $1,500 to $30,000. OneMain offers both secured and unsecured options; however, freelancers should be cautious with secured loans, as pledging assets like a vehicle puts that collateral at risk in the event of a default.
5. Xact: Flexibility in Repayment Frequency
Xact focuses on the smaller end of the credit market, with loans ranging from $500 to $5,000 and terms up to 18 months. A notable feature of Xact is the variety of payment frequencies offered—including biweekly, semimonthly, or monthly schedules. This flexibility allows freelancers to align their loan payments with the specific cadence of their client contracts. Like CreditNinja, Xact does not charge prepayment penalties, encouraging borrowers to settle their debts early if they receive a large project payout.
Statistical Context and Market Trends
The reliance on installment loans among independent workers is supported by broader economic data. According to recent labor statistics, nearly 40% of the U.S. workforce engaged in some form of freelance work over the past year. Of that group, approximately 45% reported that they live with a high degree of income uncertainty.
The shift from payday lending to installment loans is also a matter of consumer protection. Data from the Consumer Financial Protection Bureau (CFPB) suggests that the average payday loan borrower remains in debt for five months of the year due to the lump-sum repayment requirement. Installment loans, by contrast, show a higher rate of successful "graduation" out of debt, as the amortized schedule prevents the "balloon" payment that often leads to re-borrowing.
Strategic Financial Planning for the Independent Professional
Before entering into a loan agreement, financial advisors recommend that freelancers conduct a rigorous internal audit of their cash flow. This involves three primary considerations:
- The Cost of Capital: Borrowers must look beyond the monthly payment to the total cost of the loan, including the APR and any origination fees.
- The Recovery Timeline: A loan should only be used if there is a clear, documented expectation of future income (e.g., a signed contract or a pending invoice) that will cover the repayment.
- The Buffer Zone: If a freelancer’s income is so irregular that even a fixed installment payment cannot be guaranteed, they may need to seek alternative financing, such as a business line of credit, which offers more draw-and-repay flexibility than a term loan.
Impact on Credit Scores and Long-Term Viability
A significant advantage of choosing reputable installment lenders like CreditNinja or Upstart is the potential for credit building. Unlike many "off-the-grid" payday lenders, these institutions typically report payment activity to the major credit bureaus. For a freelancer, a history of on-time installment payments can strengthen their credit profile, eventually allowing them to qualify for lower-interest business credit cards or mortgage products. Conversely, a missed payment on an installment loan carries the same weight as a missed mortgage payment, making it imperative that the loan amount remains within a conservative estimate of the borrower’s "floor" income.
Conclusion: Bridging the Gap Toward Stability
As the freelance economy continues to mature, the financial products supporting it must also evolve. Personal installment loans represent a vital bridge for the modern worker, providing a structured mechanism to handle the "feast or famine" nature of independent contracting. By moving away from the guesswork of predatory lending and toward the predictability of amortized payments, freelancers can maintain their personal financial stability without compromising their professional autonomy.
However, the responsibility remains with the individual to treat these loans as a surgical tool for specific gaps. As industry leaders will likely emphasize at the 2026 10X Your Freelancing Summit, true financial freedom for the freelancer is built on a foundation of robust emergency funds and diversified client bases, with installment loans serving as a reliable safety net when the timing of the market fails to align with the demands of the calendar.
